Existing evidence
Keep photos already taken safely, the date you noticed the change and any relevant property or repair history. Do not climb onto a damaged roof to create evidence.
The roof work and the insurance payment are separate decisions. Cause, deductible, exclusions and settlement terms determine what the policy pays.
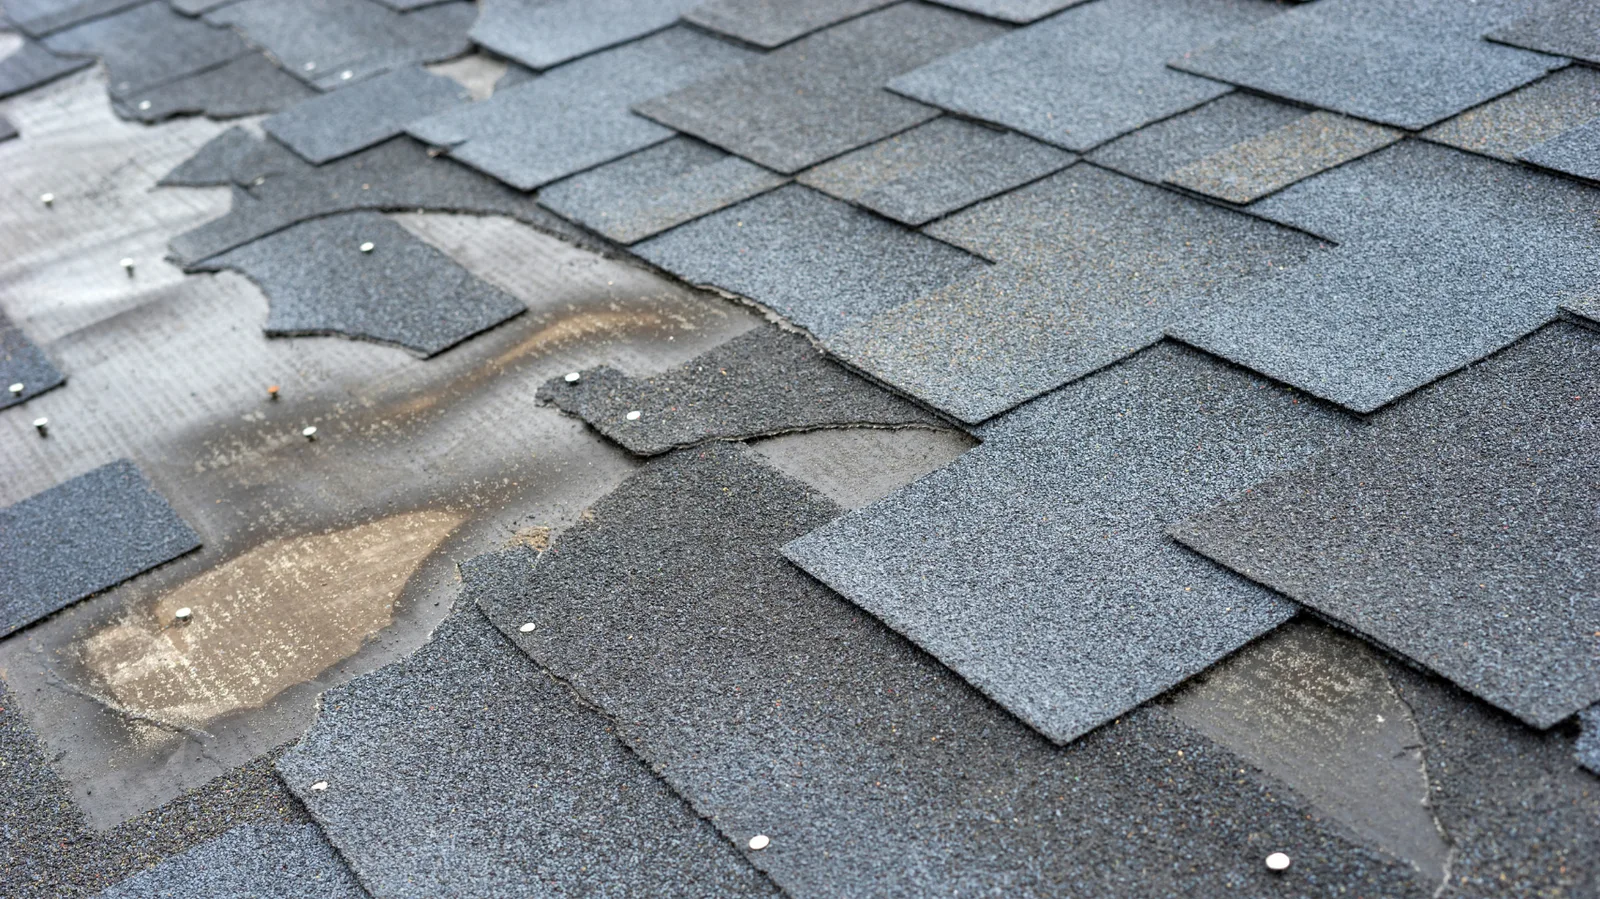
A roof can need repair without having a covered insurance loss. Storm or other sudden damage is different from ordinary wear, and a nearby hail report does not establish damage at your property.
A roofing inspection examines condition and work scope. The insurer applies the policy to the claimed cause and loss. Keep that distinction clear when discussing repairs, claim amounts and what you would pay.
Oklahoma Insurance Department guidance distinguishes these common payment terms. The actual policy and endorsements control.
| Term | What it means | Why it matters |
|---|---|---|
| Deductible | The owner’s portion under the policy. | Wind and hail can have a separate or higher deductible. |
| Actual cash value (ACV) | A settlement reflecting depreciation under the policy. | An older roof can have a payment below replacement cost. |
| Replacement cost | Coverage that can pay additional eligible amounts after repair, replacement or the policy’s required steps. | Recoverable depreciation depends on policy terms and compliance with its conditions. |
| Cosmetic damage exclusion | A restriction that can apply to surface-only damage under some policies. | A dent or mark does not alone establish a covered roof replacement. |
Useful records connect the reported event, roof condition and necessary work.
Keep photos already taken safely, the date you noticed the change and any relevant property or repair history. Do not climb onto a damaged roof to create evidence.
Take reasonable safe steps to limit further loss and retain temporary-work receipts. The policy determines any reimbursement and reporting obligations.
The physical roof estimate and the insurer’s payment calculation answer different questions. The roof cost guide gives budget context for an ordinary asphalt replacement.
Ordinary age and wear do not by themselves establish a covered loss. Coverage depends on the damage cause, policy and endorsements.
No. The cause still needs to be covered, and exclusions and settlement terms still apply. Price alone does not decide the claim.
The Oklahoma Insurance Department wind and hail guide explains deductibles, cosmetic restrictions and related roof coverage considerations.
If you have a roof damage concern, start with a free inspection to understand the condition and work involved. Policy payment remains a separate determination.